166 feeds monitored. Published Friday, September 25, 2026.
Executive Summary
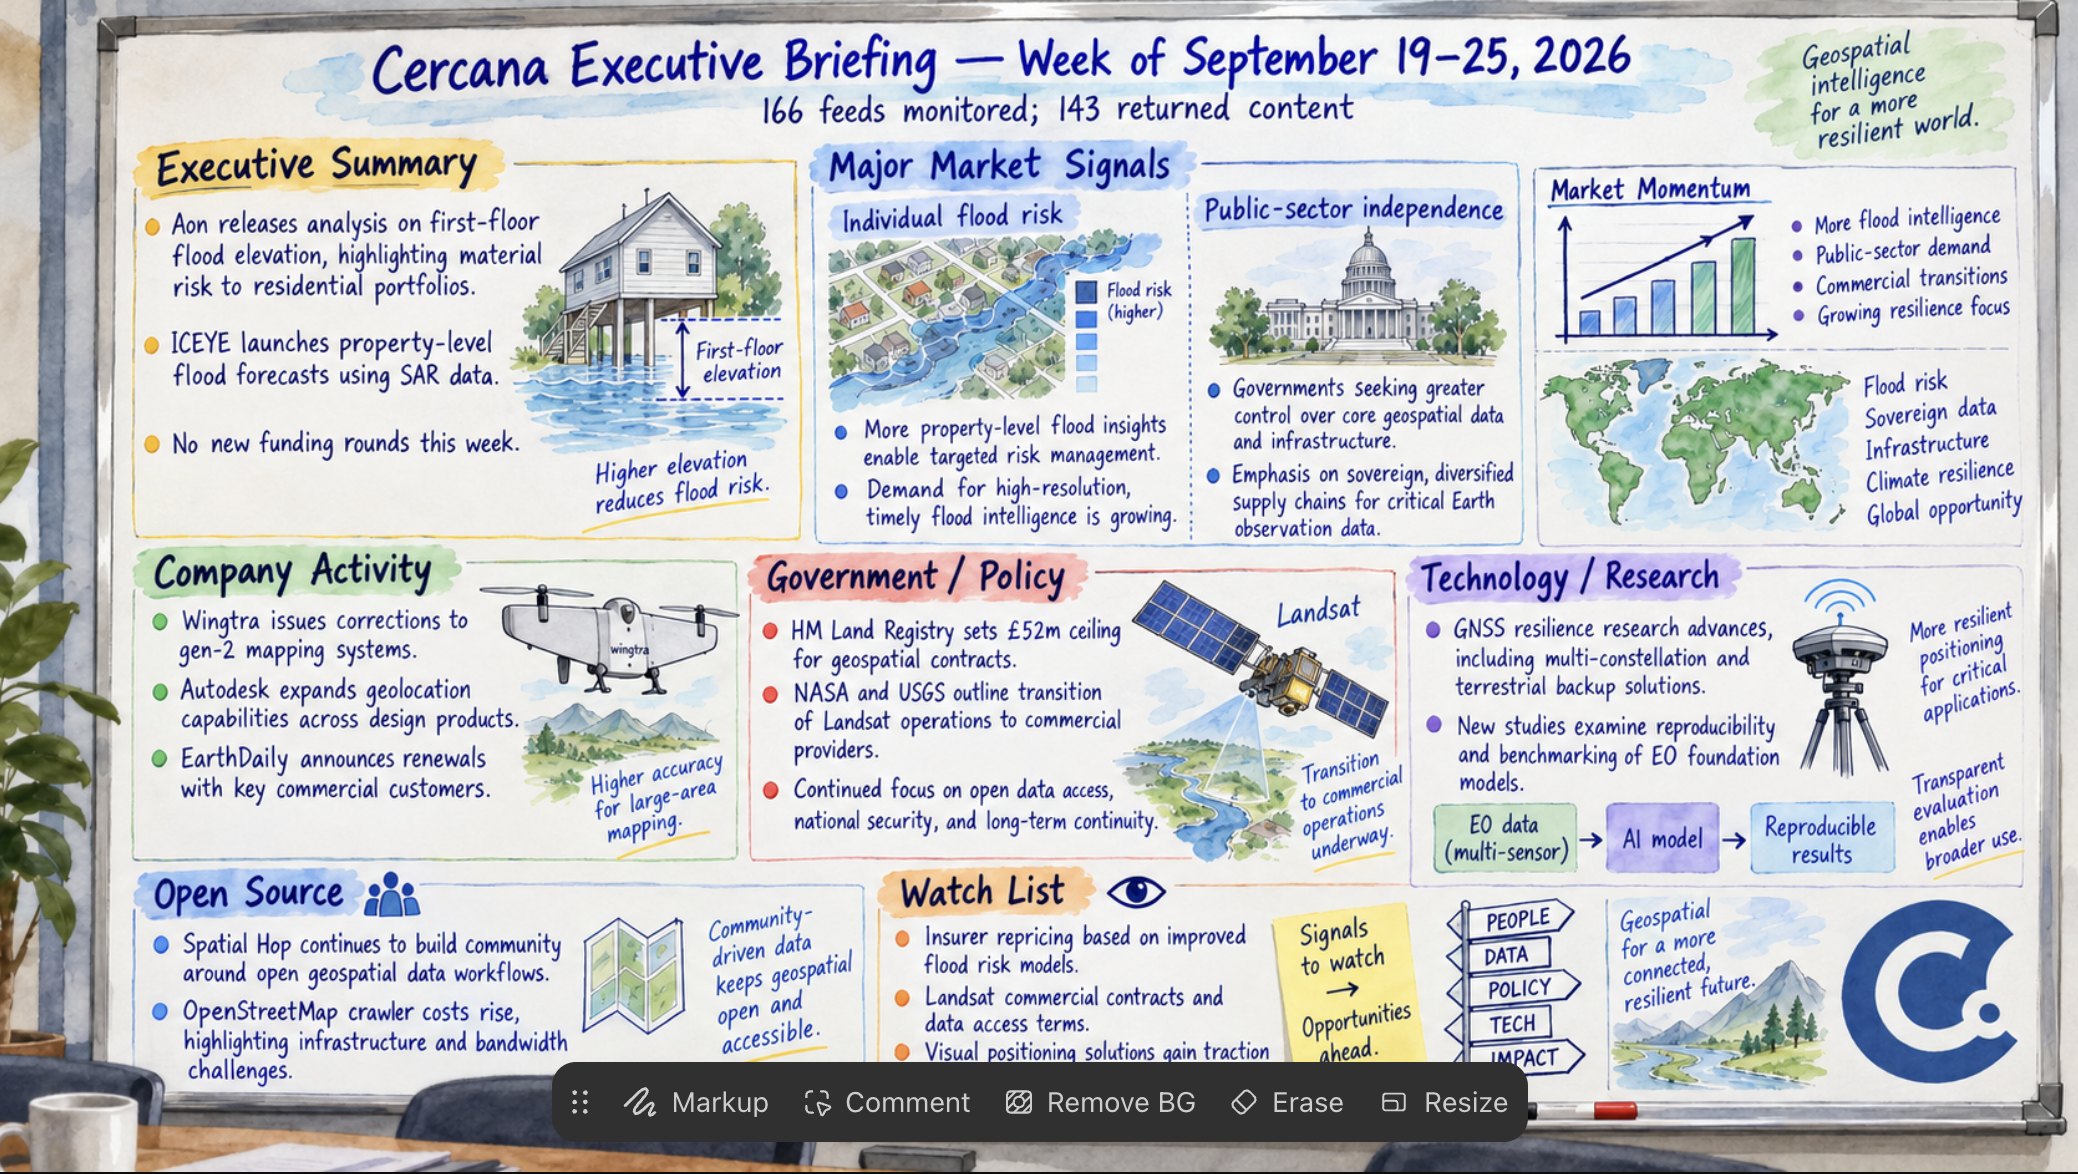
Aon and Geoscape plan to bring building-level first-floor elevation data into insurance products that reach much of the Australian market. ICEYE is working toward flood-depth forecasts for individual properties. Both efforts could give insurers a more precise view of flood risk, though neither announcement shows a carrier changing its prices.
Public agencies also raised distinct questions about control over geospatial capabilities. EUMETSAT emphasized operational autonomy, HM Land Registry wants to reduce supplier dependence, and six nations tested sovereign SAR capabilities. The available announcements say more about priorities than about changes in procurement.
No acquisitions or funding rounds surfaced in the feeds. Commercial activity centered on renewals, a UK government contract with a £52 million ceiling, and product news from INTERGEO, which ended just before this briefing window.
Major Market Signals
Building-level flood data moves closer to insurance pricing
Geoscape’s First Floor Elevation (FFE) product uses AI and ground-view imagery to estimate the height of a building’s first occupied floor. Aon says it will embed FFE across products that reach more than 90% of Australia’s insurance sector. Its initial modelling suggests that 13% of properties in flood zones could see the flood-specific portion of their premium fall by at least 50% when floor height is considered.
ICEYE, meanwhile, described plans to extend its flood service beyond observed extent and depth to forecast depth at the property level. It intends to combine physics-based modelling, weather forecasts and its archive of past events.
The efforts are independent, but both address a limitation of broad flood zones: two homes within one zone can face different levels of risk. Aon’s existing distribution gives Geoscape a route into insurers’ workflows. It doesn’t establish that insurers have changed their prices. ICEYE’s forecasting capability is also a stated direction, not yet a released product.
Confidence: Medium. Repricing by a named insurer, or a similar rollout outside Australia, would strengthen the signal.
Public agencies raise different questions about dependence
EUMETSAT’s Strategy 2040 identifies the security and resilience of its “independent and autonomous capabilities” as a priority. That concerns its ability to operate essential systems. HM Land Registry raised a different issue when it said it wants its new data modernisation partner to help build internal capability and avoid supplier dependence. At Portugal’s Space EX26 exercise, six nations tested sovereign SAR use alongside integration between allied systems.
These announcements share an interest in retaining control, but they don’t establish a common change in procurement. The available accounts disclose little about data rights, exit provisions or budgets.
Confidence: Medium that these are stated priorities; low that procurement practices have changed. Contract terms covering portability, exit rights or open standards would provide stronger evidence.
Notable Company Activity
Product Releases
- Wingtra: Released Network Corrections, a free software update that corrects drone survey data against Trimble’s permanent GNSS reference network without a local base station. Wingtra claims absolute accuracy of under 3 cm horizontally and under 6 cm vertically. The outside evidence cited is a single customer quote.
- Autodesk: Shipped a unified geolocation engine across Forma, Revit and Civil 3D at INTERGEO, according to James Fee’s Spatially Adjusted. The stated aim is to reduce repeated georeferencing as AEC teams move a site between products.
- Topcon and Sokkia: Launched reality-capture, layout and GNSS products at INTERGEO. They include receivers with anti-jamming and anti-spoofing features and handheld scanners for places where positioning is unreliable.
- Esri: Its demographic map layers retire in December 2026. Teams with dashboards that depend on them have roughly three months to migrate.
Partnerships
- Niantic Spatial and Singapore Land Authority: Signed a memorandum of understanding to study whether SLA’s aerial imagery and 3D point clouds can support a national Visual Positioning System. The announcement includes no procurement commitment.
- MentorAPM and Teledyne FLIR: Announced a technical integration that adds thermal imaging to MentorAPM’s asset-condition platform.
- Ordnance Survey and OGC: OS renewed its OGC Strategic Membership and widened the relationship through Geovation. It cited the MUDDI underground-data standard, which contributed to the UK’s National Underground Asset Register, as an example of the work it hopes to support.
Contracts, Renewals and Expansion
- EarthDaily: Two large mining companies renewed Marigold mineral-intelligence contracts, each worth six figures. One renewed after a competitive evaluation. The renewals indicate continued use, though neither customer is named.
- EagleNXT and OpenWorks: EagleNXT delivered nine US-built eBee VISION ISR kits to the Army’s National Training Center, completing an April order. OpenWorks, a UK maker of counter-UAS optics, opened a US headquarters in Virginia and plans a manufacturing site in Detroit.
Government and Policy Developments
HM Land Registry appointed Version 1 as its Data Delivery Partner. The four-year contract has a £52 million ceiling and an option for a fifth year. The ceiling is the maximum available under the contract, not committed spending. Australian coverage described the deal as “almost $100m”; that is the same contract expressed in Australian dollars, not a second award.
NASA and USGS have published a strategy for transitioning Landsat products to commercial solutions. Their goal is to produce all or most USGS Landsat products with commercially supplied data by 2035 at the latest. The plan starts with selected products, moves through demonstrations and calls for broader competition as technical requirements mature.
Project Geospatial’s analysis focuses on the business question behind that plan: can a commercial market support products that remain compatible with Landsat’s long-running public scientific record? The strategy could make the government a substantial customer for Earth-observation vendors. For users, continuity, licensing and compatibility with the historical archive remain important questions.
Overture Maps Foundation’s executive director made a related case for governments to buy foundational data once and share it across agencies. Overture has an interest in that approach, but the licensing issue it describes merits attention.
Several other items concerned the lifecycle of public data:
- USGS: Plans to switch off its legacy NWISWeb water-data system by March 2027 in favor of Water Data for the Nation. Integrations still using the old interface will need attention.
- Australia: TERN, with funding from the environment department, is building a national metadata catalogue of calibration and validation datasets, due in June 2027. It will index datasets rather than host them.
- United Nations: The General Assembly adopted its non-binding “Correct the Map” resolution on September 4, by 164 votes to one with six abstentions. It encourages wider use of equal-area projections where relative size matters. The vote preceded this briefing window.
Technology and Research Trends
Positioning resilience featured in several INTERGEO launches. Manufacturers showed GNSS receivers and antennas with anti-jamming and anti-spoofing features, along with SLAM-based scanners for places where satellite positioning degrades. These releases show what manufacturers expect buyers to need; they don’t yet show the scale of demand.
Coordinate reference systems also received more attention than usual. Alongside Autodesk’s geolocation engine, Esri UK explained upcoming ArcGIS changes that adopt country-specific ETRS89 identifiers from the EPSG registry. Existing data will continue to work, but teams moving data between software stacks may encounter mismatched names during the transition.
An ETH Zurich-led paper from the ECCV 2026 TerraBytes workshop examines the work required to turn a trained Earth-observation (EO) model into a production map. Among its examples:
- Earth Engine and ESA handle Sentinel-1 radiometry differently, so changing data providers can change a model’s inputs.
- Spatial autocorrelation can inflate reported accuracy unless validation separates locations appropriately.
- Current uncertainty methods involve trade-offs among cost, scale and calibration.
These are practical obstacles to production use. Two other releases show EO work reaching published products, though they don’t demonstrate that every issue in the paper has been resolved:
- UKCEH: Published a 3 m habitat map of England built from 12,852 satellite images.
- HZDR: Released SHABA, a tool for tracking vegetation change around mines.
Open Source Ecosystem Signals
Spatial Hop is a spatial distribution of the open-source Apache Hop data-integration platform. Its latest release replaces its GDAL/OGR dependency with a pure-Java GeoTools implementation and adds dedicated support for INTERLIS, a Swiss geodata exchange standard. The maintainer describes the trade-off plainly: fewer supported formats in exchange for a lighter build that is easier to maintain. The project appears to depend on one maintainer, which prospective adopters should consider.
Reporting from State of the Map 2026 described AI crawlers straining OpenStreetMap Foundation infrastructure and generating roughly 400 fake account registrations a day. Separately, weeklyOSM has placed a proof-of-work challenge in front of automated visitors. Both illustrate operating costs that automated traffic can impose on open geodata projects, although their effects shouldn’t be treated as one measured total.
QGIS plugin work, including an AI segmentation plugin for digitising imagery, was incremental this week.
Watch List
- Visual positioning as national infrastructure: Watch for procurement in Singapore or a similar agreement between Niantic Spatial and another mapping agency.
- US production of drones and counter-UAS equipment: Disclosed contract values or additional manufacturers establishing US facilities would help establish the scale of the shift.
- Landsat commercial transition: Demonstration contracts, published product requirements and vendor commitments to archive-compatible products will show how the strategy develops.
- AI crawler costs for open geodata: Watch for similar reports from other providers, especially ones that quantify infrastructure costs or explain changes to access.
- Mining as a paying EO market: Named customers and further contract disclosures would give a clearer commercial picture than product and dataset releases alone.
Top Posts of the Week
- AI-powered elevation data to reduce flood premiums, Spatial Source: Reports Aon’s reach, its premium modelling and the insurers represented at the launch summits.
- Insurers Have Always Known What Happened. Now They Can Know What’s Coming, ICEYE Blog: The vendor’s account of its plans for property-level flood-depth forecasting.
- HM Land Registry appoints Version 1 to £52m Data Modernisation Contract, Geoconnexion: Covers the contract and the buyer’s stated aim of building its own capability.
- The Landsat Commercial Transition: The Hard Part Is Making the Economics Work, Geospatial Frontiers – Project Geospatial: Examines the commercial questions raised by the NASA–USGS strategy.
- How to turn a machine learning model into a map, The Spatial Edge: Summarizes the reproducibility problems between an EO model and a usable map.
Cercana Executive Briefing is generated from 166 feeds aggregated by geofeeds.me.